When a distressed asset transitions into new hands through a strategic Non Performing Note Acquisition, the financial landscape shifts immediately for the portfolio manager. You sit across from a ledger of delinquent mortgages, wondering how market fluctuations, property neglect, and shifting neighborhood comps will ultimately dictate your recovery margins. Evaluating shifts in asset leverage requires a keen eye for detail, precise asset valuation techniques, and a clear understanding of the real estate cycles governing your collateral. At Buckingham-Partners, we help private lenders and institutional buyers navigate these exact portfolio adjustments with absolute clarity. Let us dive deep into the mechanics of monitoring asset leverage when dealing with distressed debt.
What is Loan to Value in distressed debt investing?
Understanding your current loan to value ratio forms the bedrock of every successful distressed debt strategy. When you purchase a delinquent mortgage at a discount, the original balance recorded on the promissory note rarely reflects the modern reality of the underlying real estate. Borrowers often default after years of deferred maintenance, local economic downturns, or environmental shifts that degrade neighborhood desirability. To protect your investment capital, you must establish a baseline leverage percentage that accounts for today’s liquidation realities rather than yesterday’s origination optimism.
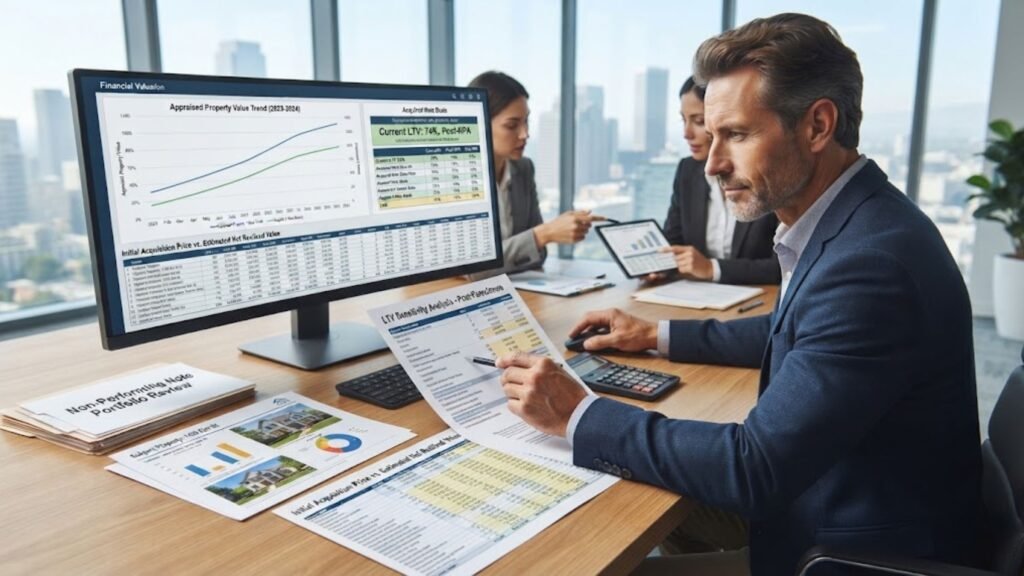
Calculating this metric involves dividing the total outstanding debt owed on the mortgage by the current appraised or broker derived value of the real property. For instance, if a borrower owes two hundred thousand dollars on a delinquent note, but the house has fallen into disrepair and is only worth one hundred fifty thousand dollars, your leverage metric sits at an uncomfortable one hundred thirty-three percent. This negative equity position means a standard foreclosure sale might not cover your acquisition costs and legal fees. Professional note buyers use sophisticated portfolio analysis tools to run sensitivity models before committing capital to any distressed pool. You can learn more about scheduling a direct strategy consultation by visiting our expert advisory scheduling page to discuss your specific note portfolio requirements.
Why collateral shifts dictate exit strategy selection
The primary driver of profitability in note investing is not just the discount you secure at purchase, but how asset leverage evolves over time. If local housing markets appreciate while you work through loss mitigation or loan modification workouts, your risk profile drops significantly. Conversely, if local property values stagnate or decline, your recovery window narrows, forcing you to pivot quickly toward alternative resolution paths. Monitoring these shifts helps you decide whether to pursue a reinstatement, a short sale, a deed in lieu of foreclosure, or traditional foreclosure proceedings.
Property condition is another massive variable that directly influences your collateral valuation over the lifecycle of the asset. A vacant home subjected to weather damage, vandalism, or copper theft can lose twenty to thirty percent of its market value in a matter of months. Regular drive-by inspections, occupancy checks, and exterior evaluations are mandatory protocols for keeping your collateral data accurate. By maintaining rigorous oversight of these physical changes, you ensure that your investment decisions rely on verified data rather than outdated assumptions.
Assessing market trends and neighborhood dynamics
Local economic indicators play a massive role in shaping how collateral values shift after you take ownership of a distressed debt instrument. Job growth rates, regional migration patterns, municipal zoning updates, and school district ratings all contribute to neighborhood desirability. When assessing a pool of non-performing mortgages, you must look beyond the individual property fence line and analyze the broader metropolitan statistical area.
| Economic Indicator | Impact on Distressed Notes | Monitoring Frequency |
| Local Employment Rates | Directly affects borrower re-performance potential | Quarterly Review |
| Neighborhood Foreclosure Density | Influences comparable sales and market absorption | Monthly Tracking |
| Municipal Infrastructure Projects | Can boost or depress local property equity values | Bi-Annual Check |
| Zoning and Land Use Changes | Alters highest and best use potential for collateral | Annual Audit |
Neighborhood appreciation can often bail out an otherwise struggling asset acquisition by naturally lowering your risk exposure over time. If you acquire a debt instrument at a steep discount in a revitalizing urban core, neighborhood gentrification might push property prices upward. This organic growth helps offset legal expenses and holding costs accrued during the judicial or non-judicial resolution process. You can explore our core philosophy and historical track record by visiting the main corporate website to see how we approach asset evaluation.
Financial modeling for post-acquisition adjustments
Financial modeling in the distressed debt space requires dynamic spreadsheets that account for multiple variables, including legal fees, servicing costs, and holding timelines. When you update your financial models following an acquisition, you must factor in the friction costs associated with asset recovery. Every month a borrower remains in default without making payments, taxes accumulate, insurance must be force-placed, and legal retainers increase.
| Cost Category | Typical Expense Range | Effect on Equity Margin |
| Legal and Foreclosure Fees | Two thousand to seven thousand dollars | Directly reduces net recovery proceeds |
| Property Preservation | Five hundred to five thousand dollars | Protects collateral value from degradation |
| Broker Price Opinions (BPOs) | One hundred to three hundred dollars | Essential for accurate equity tracking |
| Administrative Servicing | Fifty to one hundred dollars monthly | Ongoing operational overhead |
These ongoing expenses eat into your projected profit margins if left unchecked for too long. Therefore, updating your financial models on a monthly or quarterly basis ensures that you never chase a bad asset with good money. If the numbers indicate that a full foreclosure will yield a net loss due to surging costs and sluggish market appreciation, selling the note to another investor becomes a rational alternative.
Practical steps for managing delinquent mortgage portfolios
Executing a repeatable workflow for monitoring distressed assets separates amateur investors from seasoned institutional professionals. Once you finalize a Non Performing Note Acquisition, your asset management team should immediately implement a structured review calendar.
- Order fresh broker price opinions or full appraisals to establish an accurate baseline of the physical collateral.
- Review the complete chain of title to ensure no hidden junior liens, municipal tax judgments, or environmental encumbrances threaten your position.
- Contact the borrower through licensed third-party servicers to explore voluntary workout options before initiating legal action.
- Establish a dedicated escrow tracking system to monitor delinquent real estate taxes and hazard insurance premiums proactively.
Implementing these steps safeguards your invested capital and positions your portfolio for maximum risk-adjusted returns. For personalized guidance on structuring your next transaction or auditing an existing pool of delinquent mortgages, reach out to our team directly through our secure inquiry portal to start a conversation today.
Frequently Asked Questions
What happens if the collateral value drops below the total debt owed?
When property values fall below the total debt balance, you enter a deficiency or high-risk leverage state. This means a standard foreclosure sale may not recover your total investment, requiring you to carefully weigh legal costs against potential loss mitigation outcomes like structured repayment plans or short sales.
How often should investors re-evaluate their asset leverage metrics?
Institutional investors typically review leverage metrics on a quarterly basis or whenever significant regional economic shifts occur. For highly volatile or declining real estate markets, monthly monitoring of broker price opinions and local comparable sales is strongly recommended.
Why is a title search critical after acquiring a distressed mortgage?
A thorough title search uncovers hidden encumbrances such as unpaid municipal water bills, local code enforcement liens, or senior tax certificates that could jump ahead of your mortgage lien position and jeopardize your recovery strategy.
Can property neglect completely wipe out anticipated profit margins?
Yes, severe deferred maintenance, structural water damage, or vandalism can drastically reduce the market value of the underlying real estate. This makes regular exterior inspections and proactive property preservation essential components of modern note investing.
How does Non Performing Note Acquisition fit into a diversified investment portfolio?
This strategy allows experienced investors to acquire real estate debt at steep discounts, providing alternative yields uncorrelated with traditional stock and bond markets. Success depends heavily on meticulous asset valuation, rigorous legal compliance, and disciplined portfolio management.
Conclusion
Navigating the complexities of distressed debt requires a disciplined approach to tracking market dynamics, property conditions, and financial models. By carefully monitoring your asset leverage and adapting your resolution strategies to real-time data, you can transform delinquent debt into a profitable investment vehicle. Mastering a Non Performing Note Acquisition demands patience, analytical rigor, and a commitment to continuous portfolio auditing. Partnering with seasoned professionals ensures that you remain protected against unforeseen market downturns and legal hurdles.